Guides · 6 Oct 2026 · 4 min read
ETF vs mutual fund: the real differences, explained simply
ETFs and mutual funds can hold exactly the same investments. The differences are in how you buy them, what they cost and how they're taxed.
The short answer
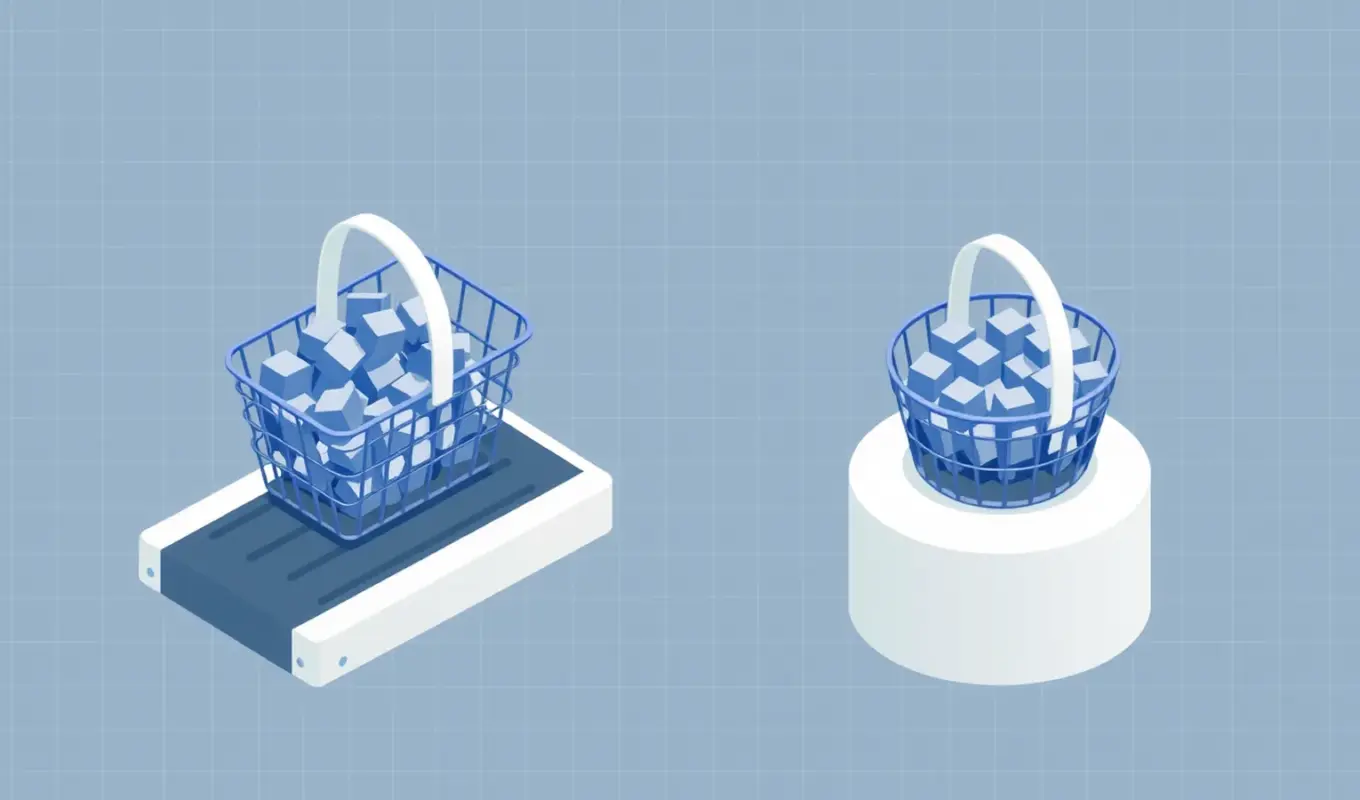
ETFs and mutual funds both pool investors' money into a basket of securities. ETFs trade on a stock exchange throughout the day at market prices, while mutual funds are bought and sold once a day at a price set after the market closes. ETFs often have lower fees and, in some countries, better tax efficiency; mutual funds can make automatic monthly investing easier.
Key takeaways
- The structure differs; the investments inside can be identical.
- ETFs trade all day like shares; mutual funds price once a day.
- Compare total costs: the fund fee plus any trading or platform charges.
- For automatic monthly investing, check which format your platform handles best.
Search for almost any investment and you’ll find it offered as an exchange-traded fund (ETF), a mutual fund, or both. The ETF vs mutual fund question confuses a lot of beginners because, underneath, they can hold exactly the same things. The differences are about how they’re traded, what they cost and how they’re taxed.
What do ETFs and mutual funds have in common?
Both are pooled investments. Thousands of investors put money in, and a fund company uses it to buy a basket of stocks, bonds or other assets. You own units of the fund, and the value of your units moves with the value of the basket.
Both come in two broad styles:
- Index (passive): track a market index at low cost. See what is an index fund.
- Active: a manager picks investments to try to beat the market, usually for a higher fee.
So “ETF vs mutual fund” is not the same question as “passive vs active.” There are active ETFs and passive mutual funds.
The key differences between ETFs and mutual funds
| ETF | Mutual fund | |
|---|---|---|
| How you buy | On a stock exchange through a broker, like a share | Directly from the fund company or via a platform |
| When it’s priced | Continuously during market hours | Once a day, after the market closes (net asset value) |
| Price you pay | Market price, plus a small bid-ask spread | That day’s net asset value |
| Minimum investment | One share (or a fraction) | Varies; some have minimums |
| Typical fees | Often very low for index ETFs | Low for index funds; higher for active funds |
| Automatic monthly investing | Depends on the platform | Usually easy |
| Tax efficiency (US) | Usually higher | Can distribute capital gains |
How does trading differ?
ETFs trade like shares. You can buy or sell at 10:15am or 3:45pm, and you see the price before you trade. You can also use order types such as limit orders. The trade-off is a small bid-ask spread, the gap between the buying and selling price, which is tiny for large, popular ETFs and wider for niche ones.
Mutual funds trade once a day. You place an order and it’s filled at the next calculated net asset value (NAV), after the market closes. You won’t know the exact price in advance. For long-term investors who buy monthly, that rarely matters.
Being able to trade all day is only useful if you need it. For most long-term investors, the ability to trade instantly is a temptation rather than a benefit.
Which is cheaper, an ETF or a mutual fund?
Compare total cost, not just the headline fee:
- Ongoing charge / expense ratio — the annual fee taken by the fund. Broad index ETFs and index mutual funds can both be very cheap; the gap is often small.
- Trading costs — some brokers charge commissions on ETF trades, while others offer them free. Platforms may charge for mutual fund dealing.
- Platform or account fees — a percentage or flat fee charged by the platform itself, regardless of fund type.
- Bid-ask spread — applies to ETFs only; negligible for big funds.
A difference of a few hundredths of a percent rarely matters. A difference of 0.5–1% a year matters enormously over decades.
How are ETFs and mutual funds taxed?
Tax rules depend on your country and account type, and inside a tax-advantaged retirement account the difference often disappears.
In the United States, ETFs are generally more tax-efficient in taxable accounts. Their creation and redemption process lets them avoid selling holdings for cash, so they rarely pass on capital gains distributions. Mutual funds sometimes have to sell holdings when investors redeem, which can create a taxable distribution even if you didn’t sell anything.
Outside the US, check how funds are classified for tax where you live; some countries treat foreign-domiciled ETFs differently.
Which should you choose?
Ask yourself four questions:
- Does my platform let me invest automatically every month in this format? Automation, such as dollar-cost averaging, is the habit that builds wealth.
- What’s the total cost? Fund fee plus trading and platform charges.
- Am I investing in a taxable account? If so, tax efficiency deserves weight.
- Is the fund large and well established? Bigger funds tend to have tighter spreads and lower risk of closure.
If two options track the same index at a similar total cost, either is a reasonable choice. The decision that matters far more is your mix of stocks and bonds and how consistently you invest.
Watch out for these types
Both ETFs and mutual funds can hide complexity behind a familiar label:
- Leveraged and inverse ETFs aim for multiples (or the opposite) of daily returns and can lose value over time even when the index ends flat. They are built for short-term trading, not long-term holding.
- Narrow thematic funds (for example a single technology trend) can be highly concentrated and volatile.
- High-fee active funds must outperform by more than their fee just to match a cheap index fund.
The bottom line
ETFs and mutual funds are two wrappers for the same idea. ETFs offer intraday trading, often lower fees and, in the US, better tax efficiency. Mutual funds can make automatic investing simpler. Choose the format that keeps your total costs low and makes it easiest to invest regularly, then focus on the bigger decisions in how to start investing.
This guide is general information, not personal financial advice. Tax treatment depends on individual circumstances and may change.
Frequently asked questions
Are ETFs better than mutual funds?
Not automatically. A low-cost index mutual fund and a low-cost index ETF tracking the same index will deliver almost the same result. ETFs tend to win on fees and flexibility; mutual funds can be simpler for automatic investing on some platforms.
Can I lose money in an ETF?
Yes. An ETF is only as safe as what it holds. A stock ETF rises and falls with the stock market, and specialist ETFs (leveraged, single-sector or crypto) can be much more volatile.
Do ETFs pay dividends?
Many do. Distributing ETFs pay out dividends from the companies they hold, while accumulating ETFs reinvest them automatically. Mutual funds offer the same two options.
What is the minimum investment for an ETF?
Usually the price of one share, and many brokers now allow fractional shares, so you can start with a few dollars. Some mutual funds have minimum initial investments, though many platforms have lowered or removed them.
Sources: Investor.gov (U.S. SEC) — Introduction to Investing, FINRA — Investing basics