Guides · 6 Oct 2026 · 3 min read
Sinking funds: the simple trick that stops expenses wrecking your budget
Car repairs, annual bills, holidays and gifts aren't emergencies — they're predictable. Sinking funds spread them across the year so they never catch you off guard.
The short answer
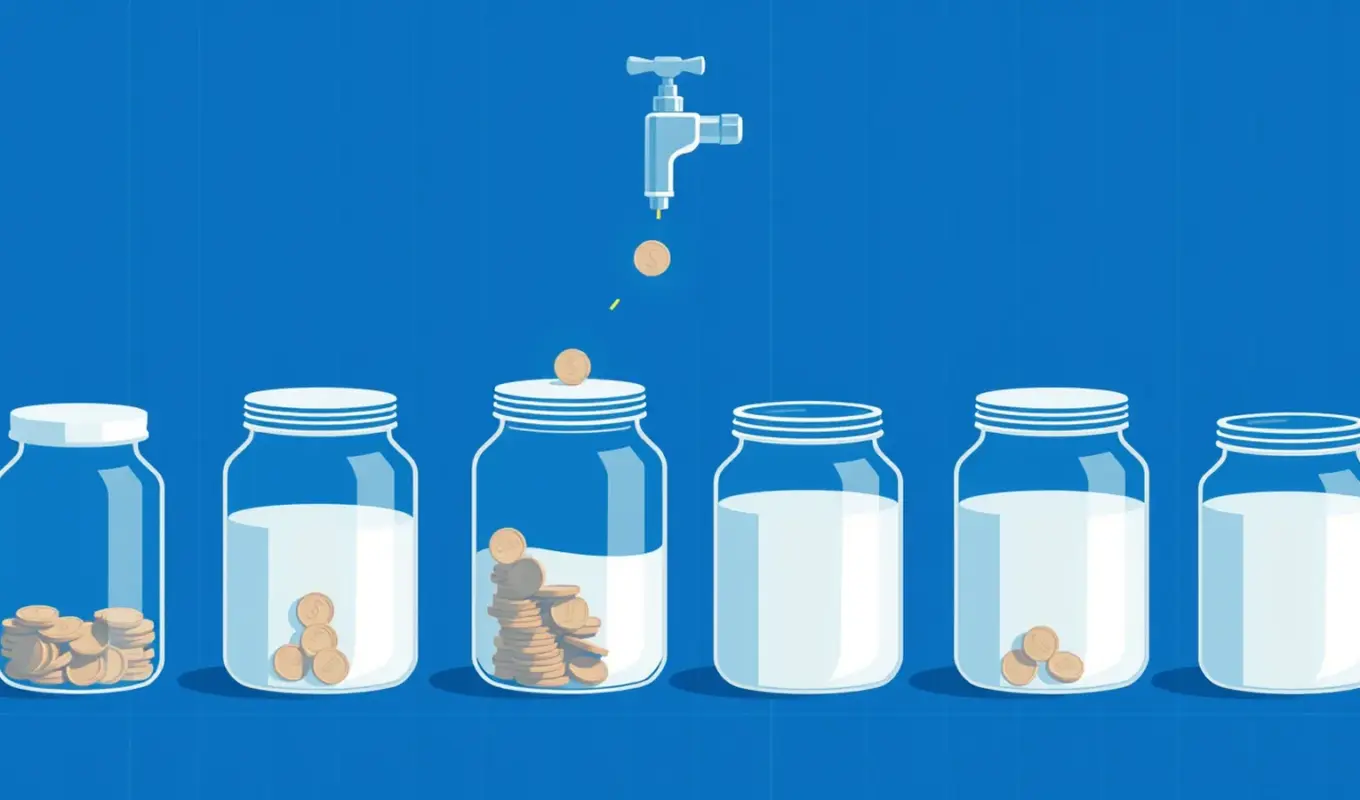
A sinking fund is money you set aside a little at a time for a specific, predictable future expense, such as car maintenance, annual insurance, holidays or gifts. You divide the expected cost by the number of months until it's due and save that amount monthly, so the bill is already covered when it arrives and doesn't come out of your emergency fund or a credit card.
Key takeaways
- Sinking funds are for predictable costs; emergency funds are for surprises.
- Monthly amount = expected cost ÷ months until it's due.
- Common categories: car, insurance, holidays, gifts, home repairs, tech.
- Use labelled 'pots' or sub-accounts so each goal is visible.
Most budgets don’t fail because of daily spending. They fail when the car insurance renewal arrives, the boiler needs a service and three family birthdays land in the same month. Sinking funds fix that by turning lumpy, predictable costs into small monthly amounts.
What is a sinking fund?
A sinking fund is money you set aside gradually for a specific future expense you can see coming. The term comes from corporate finance, where companies put aside money over time to repay a debt. In personal finance, it simply means: save a little each month so a known bill is already paid for when it arrives.
Sinking fund vs emergency fund
| Sinking fund | Emergency fund | |
|---|---|---|
| Purpose | Predictable, planned costs | Unexpected, necessary costs |
| Examples | Car insurance, holidays, gifts, annual subscriptions | Job loss, medical bills, urgent repairs |
| Amount | Based on the expected cost | Based on 3–6+ months of essentials |
| Spending it | Planned and expected | Only in a genuine emergency |
Without sinking funds, predictable costs end up coming out of your emergency fund or going on a credit card. Separating them protects both your safety net and your budget.
How do you calculate a sinking fund?
The formula is simple:
Monthly amount = expected cost ÷ months until it’s due
Examples:
| Expense | Cost | Due in | Monthly amount |
|---|---|---|---|
| Annual car insurance | $600 | 12 months | $50 |
| Car maintenance and tyres | $1,800 | 12 months | $150 |
| Summer holiday | $2,400 | 10 months | $240 |
| Holiday gifts | $600 | 12 months | $50 |
If you’re starting late, the monthly amount will be higher. Next year, start earlier and it drops.
Which sinking funds should you have?
Look back over your bank statements for the last 12 months and list every cost that didn’t happen monthly. Common categories:
- Car: insurance, servicing, tyres, registration, repairs
- Home: maintenance, appliance replacement, annual service contracts
- Insurance: any annual or quarterly premiums
- Holidays and travel
- Gifts and celebrations: birthdays, weddings, festive season
- Health: dental, glasses, prescriptions not covered by insurance
- Technology: replacing a phone or laptop every few years
- Annual subscriptions and memberships
- Pets: vet visits, vaccinations
- Kids: school trips, uniforms, activities
Start with the three to five biggest. You can always add more.
How to set up sinking funds
- List the expenses and costs using last year’s statements.
- Calculate monthly amounts with the formula above.
- Open a place to keep them. Many banks let you create named sub-accounts or “pots” within a savings account; that keeps each goal visible. A high-yield savings account earns interest while the money waits.
- Automate the transfers on payday, right after your regular savings. Our guide on how to make a budget shows how sinking funds fit into a monthly plan.
- Spend from the fund when the bill arrives — that’s what it’s for.
- Review once or twice a year and adjust amounts as costs change.
Tips to make sinking funds work
- Round up. Costs tend to rise; slightly over-saving beats coming up short.
- Combine small categories into one “annual bills” fund if many small pots feel fiddly.
- Roll leftovers forward or move them to a goal such as investing.
- Don’t raid one fund for another unless you top it back up.
- Keep it simple. A system you maintain beats a perfect one you abandon.
Common sinking fund mistakes
- Underestimating costs. Use last year’s real bills, not guesses, and add a margin for price rises.
- Forgetting the long-cycle items. A laptop every four years or a new roof every twenty still needs a monthly contribution, even if it’s small.
- Mixing them with your emergency fund. If both sit in one balance, it’s easy to spend your safety net on a holiday without noticing.
- Starting too many at once. Ten tiny pots can feel overwhelming. Cover the big three to five first, then expand.
- Stopping after the bill is paid. The next renewal is already on its way; keep the transfer running.
Why sinking funds make such a difference
Sinking funds turn financial shocks into non-events. The car service is just a planned withdrawal, the holiday is paid for before you go, and the festive season doesn’t spill into January’s credit card bill. That stability also makes it easier to keep paying down debt and investing consistently. See debt avalanche vs snowball and how to start investing.
The bottom line
Sinking funds are one of the simplest tools in personal finance: identify predictable irregular costs, divide by the months until they’re due, and save that amount automatically. Your budget becomes calmer, your emergency fund stays intact, and big bills stop being surprises.
This article is general information, not personal financial advice.
Frequently asked questions
What is the difference between a sinking fund and an emergency fund?
A sinking fund is for expenses you know are coming, like annual insurance or a holiday. An emergency fund is for the unexpected, like job loss or urgent repairs. Keeping them separate stops planned spending from draining your safety net.
How many sinking funds should I have?
Start with three to five covering your biggest irregular costs, often car, insurance, holidays and gifts. You can add more later, but too many small funds can become hard to manage.
Where should I keep sinking funds?
In an easy-access savings account, ideally one that lets you create named sub-accounts or pots. A high-yield savings account means the money earns some interest while it waits.
Is a sinking fund the same as saving?
It's a specific type of saving with a defined purpose, amount and deadline. That structure makes it easier to stay on track than saving into one general pot.
Sources: Consumer Financial Protection Bureau — Budgeting and saving, FINRA Foundation — Personal finance resources